

The cloud is clearly a sunrise industry. India will consume much more computing, storage, cyber security and AI infrastructure ten years from now than it does today.
That makes ESDS interesting. It does not automatically make the ESDS IPO attractive.
At the upper price band of ₹429, the post-issue equity value is roughly ₹5,028 crore. Against that, ESDS reported FY26 revenue of ₹472 crore, PAT of ₹121 crore and a headline EBITDA margin of almost 50%.
The ₹720 crore issue is entirely fresh equity. Bidding runs from August 28 to September 1, 2026, the lot size is 34 shares and listing is expected on September 4.
Those numbers look excellent. The disclosures underneath them do not give me the same comfort.
I think this is a poor-quality IPO proposition. I do not need to prove fraud to decide that I do not want to own the company. What the documents establish is a collection of unusual facts that collectively destroy my confidence in the earnings, cash flow, governance and valuation story.
Here are the six that matter most.
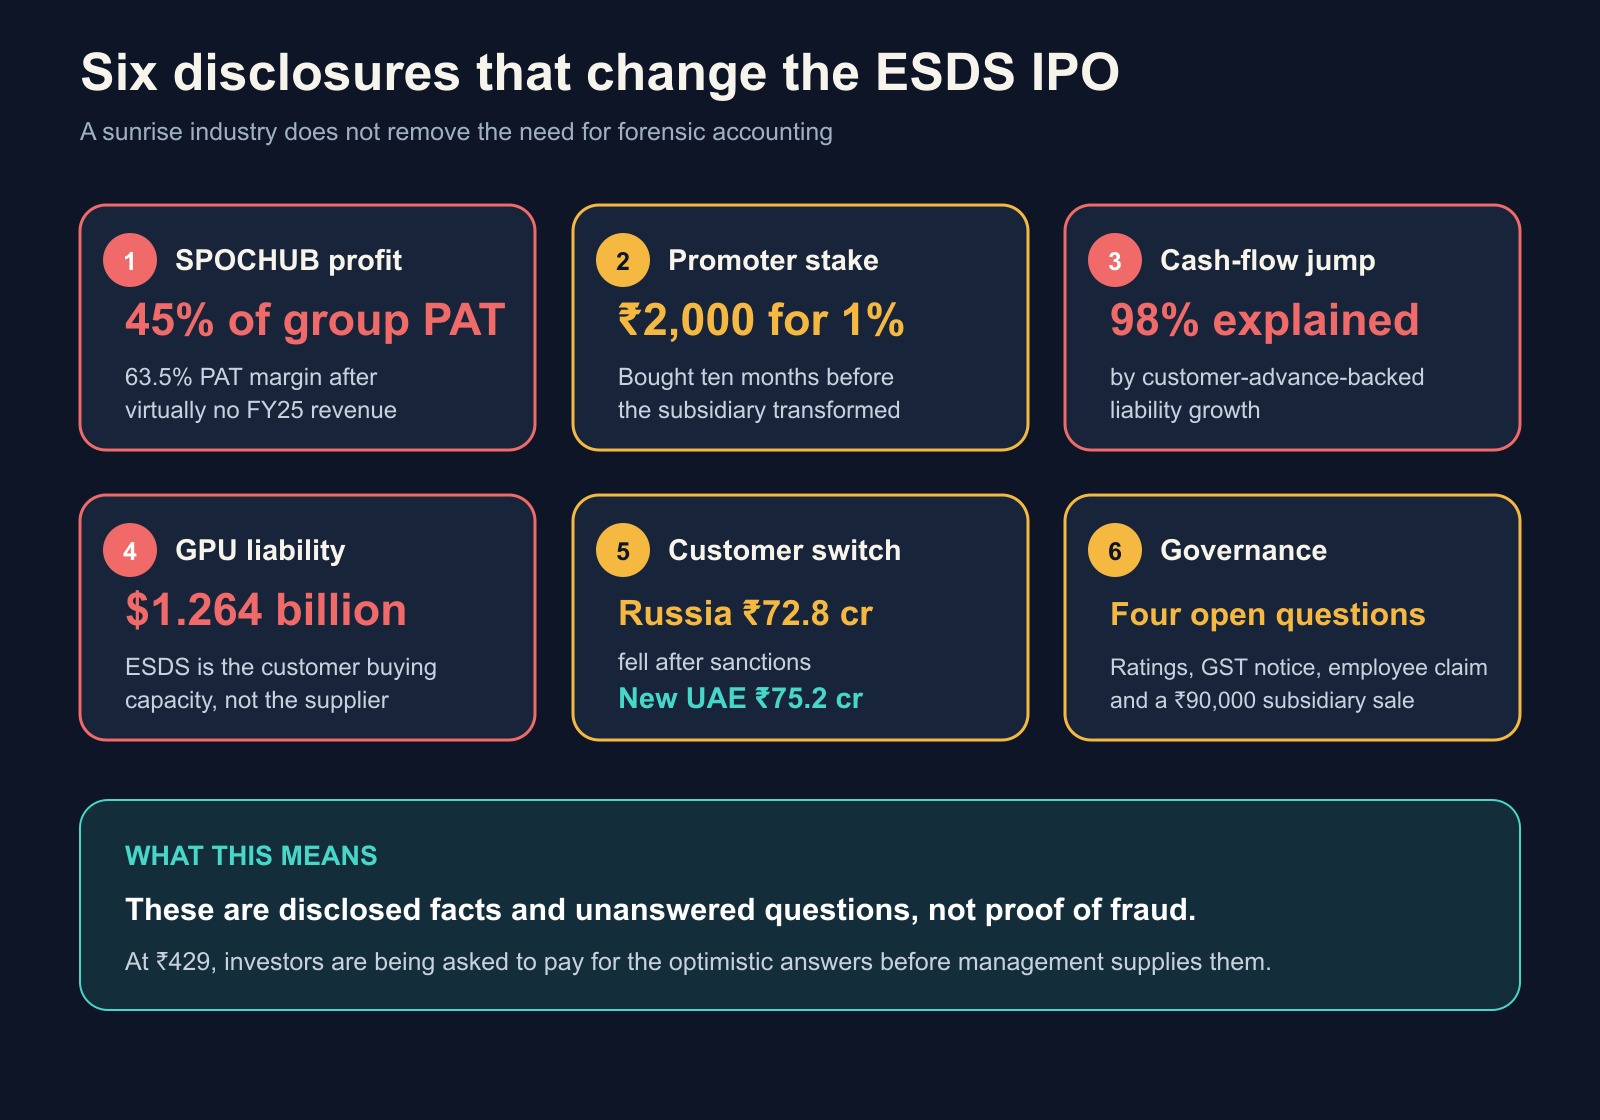
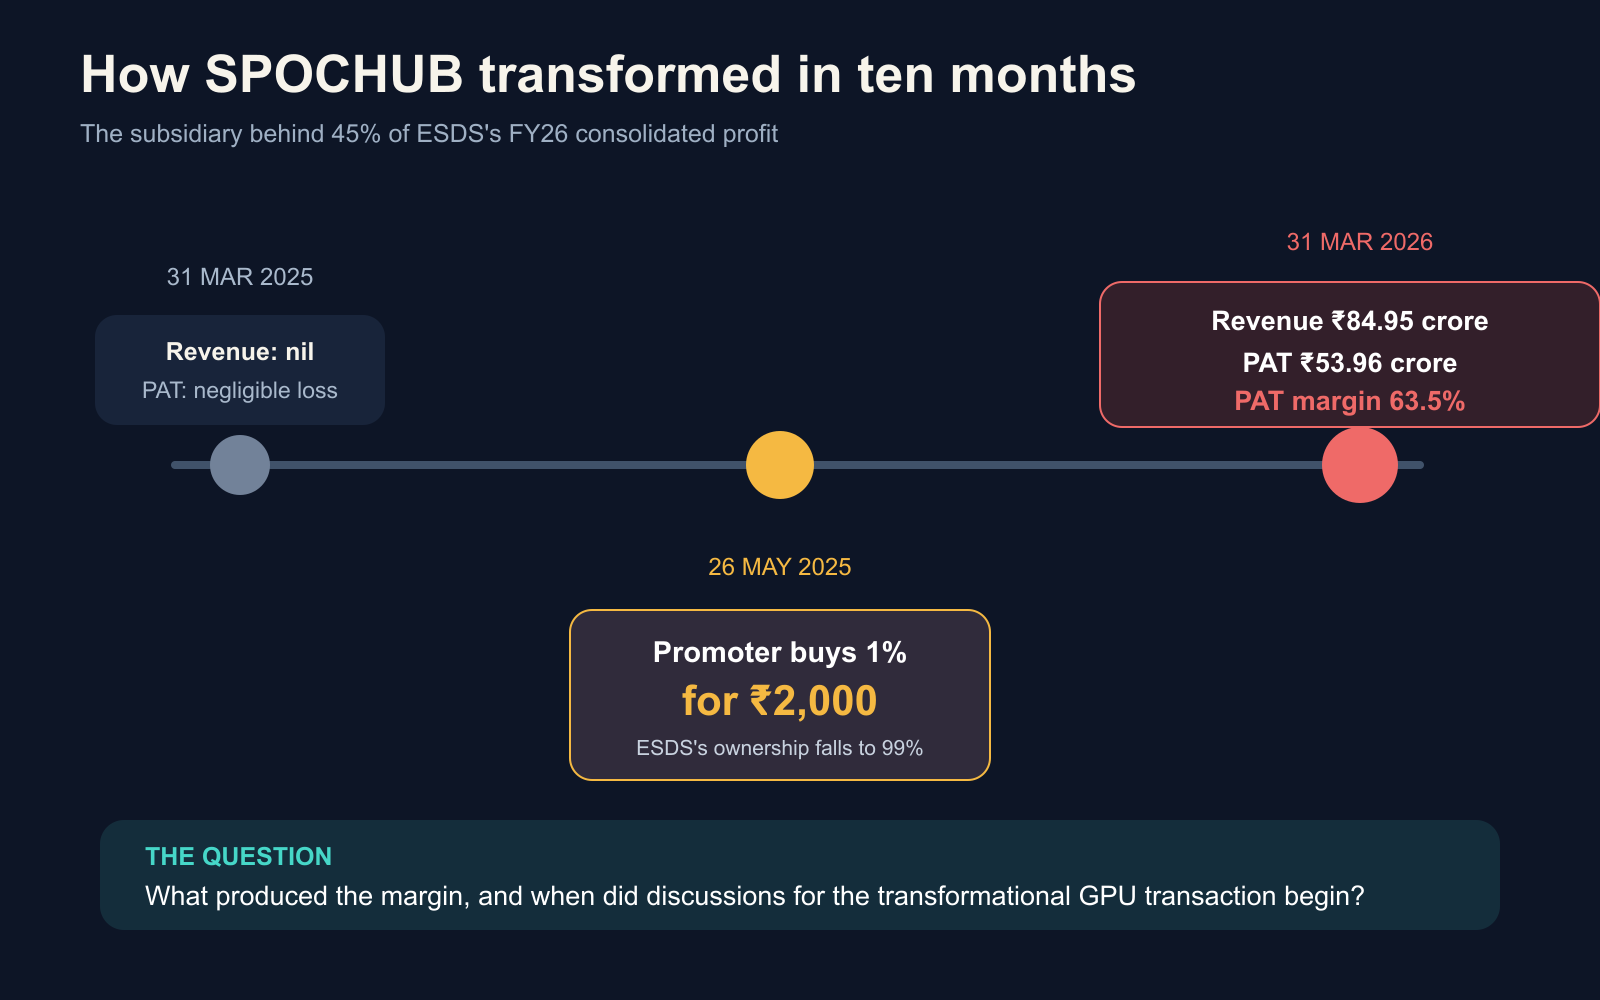
First, almost 45% of FY26 consolidated PAT came from SPOCHUB, a subsidiary that had virtually no revenue in FY25. It reported a remarkable 63.5% PAT margin in its first meaningful year of operation.
Second, the promoter personally bought 1% of SPOCHUB from ESDS for ₹2,000 in May 2025. Ten months later, the subsidiary reported ₹53.96 crore of PAT and ₹54.21 crore of net worth.
Third, the reported ₹1,368 crore operating cash flow includes roughly ₹1,181 crore of increase in liabilities, mainly because of a customer advance. That advance is money received before future service delivery, not recurring cash profit.
Fourth, the much-discussed $1.25 billion AI agreement is not a $1.25 billion customer order for ESDS. The US filings show that ESDS and its subsidiaries are the customer buying dedicated GPU capacity from SharonAI. The liability is visible in great detail. The matching onward customer contract is not.
Management’s latest media interviews make this disclosure problem worse. The same arrangement has repeatedly been discussed as a giant deal or contract, management has said GPUs are behaving like appreciating assets, and a $14 billion business funnel has been presented without the information required to treat it as an order book.
Fifth, a Russian customer that generated ₹72.8 crore in FY25 fell to ₹13.2 crore after sanctions. In FY26, a new UAE customer appeared and generated ₹75.24 crore. There is no evidence that these customers are connected, but the near replacement of one concentrated overseas account with another deserves explanation.
Sixth, there are governance disclosures that should not be ignored, including multiple ratings carrying an issuer-not-cooperating label, a pending GST notice alleging wrongful input-tax credit based on fraudulent invoices, and a former employee’s pending claim that he was promised shares.
My conclusion is simple.
My recommendation is simple. I would not apply to the ESDS IPO. I think my subscribers should stay away.
Every unanswered question does not need a sinister answer for the IPO to be unattractive. Investors are being asked to pay more than ₹5,000 crore before the most important questions have answers.
What ESDS sells, in one minute
ESDS operates data centres and sells cloud infrastructure, managed services and software to Indian government bodies, banks and enterprises. Its pitch is local hosting, regulatory compliance and hands-on support.
That is a sunrise market. It is not a unique market. Customers can use global hyperscalers, Indian cloud providers, data-centre operators, systems integrators and specialised software vendors. ESDS has certifications, customer relationships and switching costs, but I do not see evidence of a moat strong enough to make the red flags irrelevant.
The IPO story has now become heavily dependent on SPOCHUB and a giant GPU-as-a-service project. That is where the analysis should begin.
The financial story looks spectacular at first sight
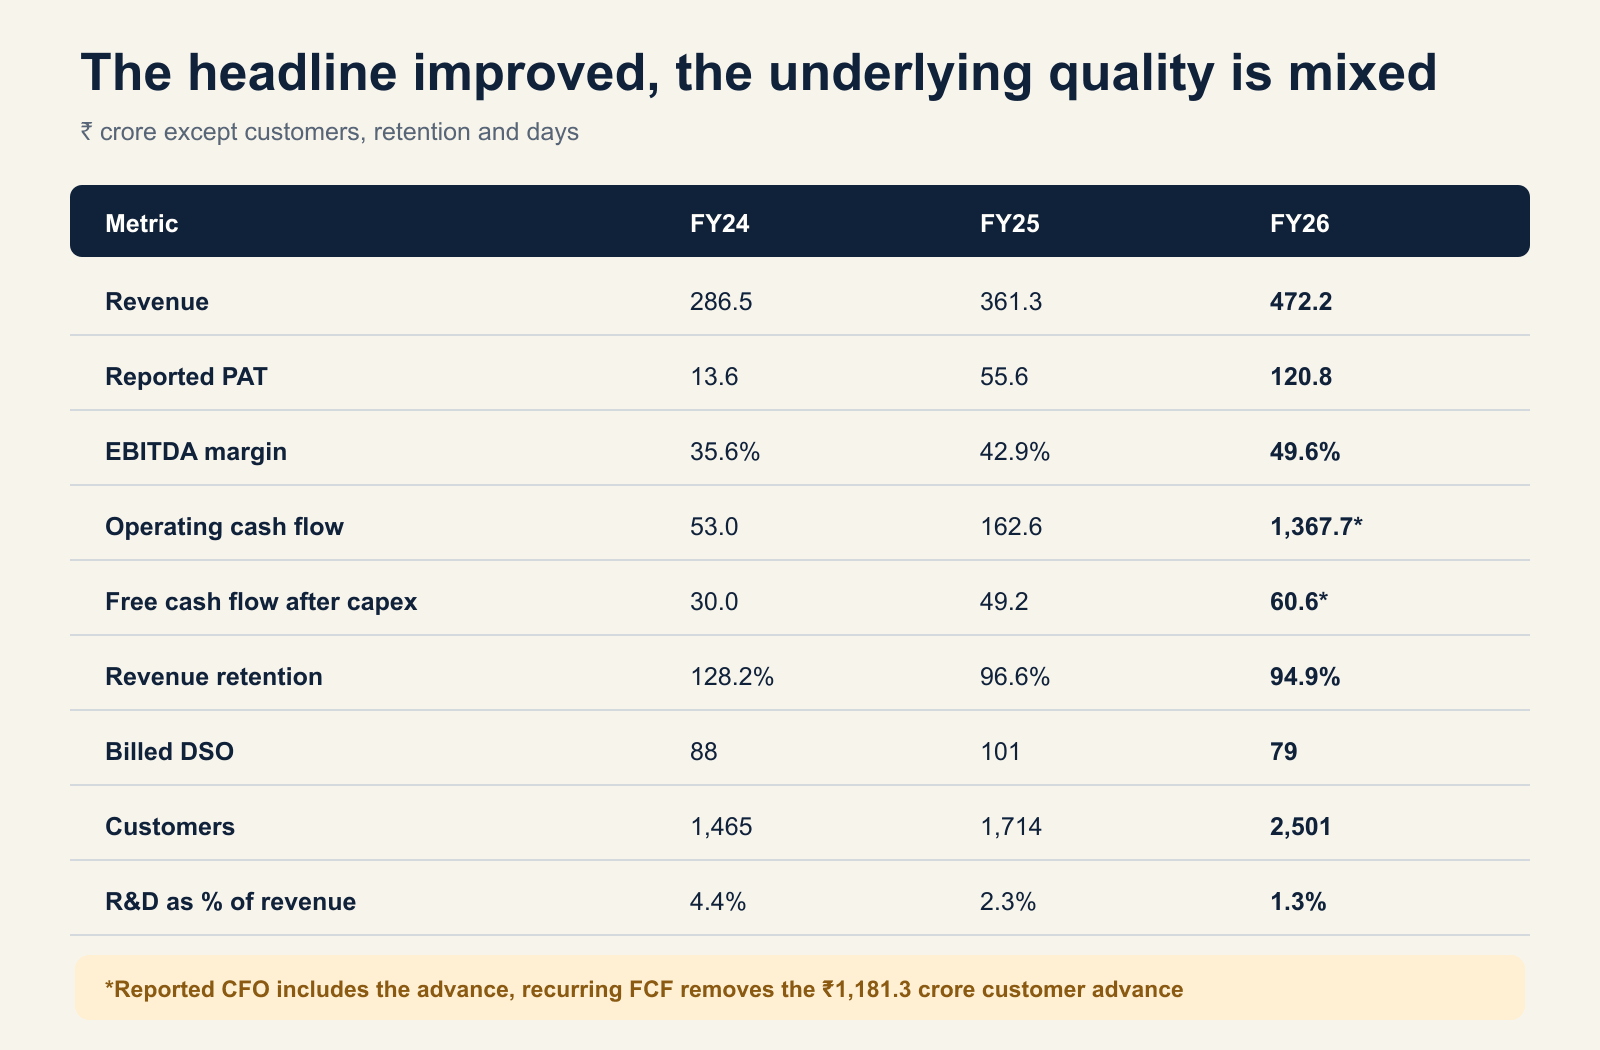
Revenue grew from ₹287 crore in FY24 to ₹472 crore in FY26. PAT grew from ₹14 crore to ₹121 crore. Reported EBITDA margin rose from 35.6% to 49.6%.
The IPO is entirely fresh capital and ₹576 crore is earmarked for new infrastructure. That may sound comforting, but fresh capital does not repair weak disclosure or make unusual earnings high quality. The composition of the reported numbers matters more than the headline growth.
One smaller adjustment is worth remembering. FY25 other income included ₹10.49 crore from cessation of lease liabilities. That was material against FY25 PAT of ₹55.6 crore and did not recur in FY26. The underlying business improved, but the neat PAT growth line contains different sources of profit in different years.
Red flag 1: the subsidiary that went from zero to 45% of group PAT
SPOCHUB reported FY26 revenue of ₹84.95 crore and PAT of ₹53.96 crore. In FY25 and FY24, it reported no revenue and a negligible loss.
The consolidated group reported PAT of ₹120.82 crore.
This means SPOCHUB contributed roughly 45% of reported group PAT in FY26. A simple subtraction leaves about ₹66.9 crore for the rest of the group, compared with ₹55.6 crore of consolidated PAT in FY25.
The subtraction is approximate because consolidated accounts can contain eliminations, but the direction is unambiguous. The mature business did not suddenly double its profit. A new overseas enterprise engagement created a large part of the jump.
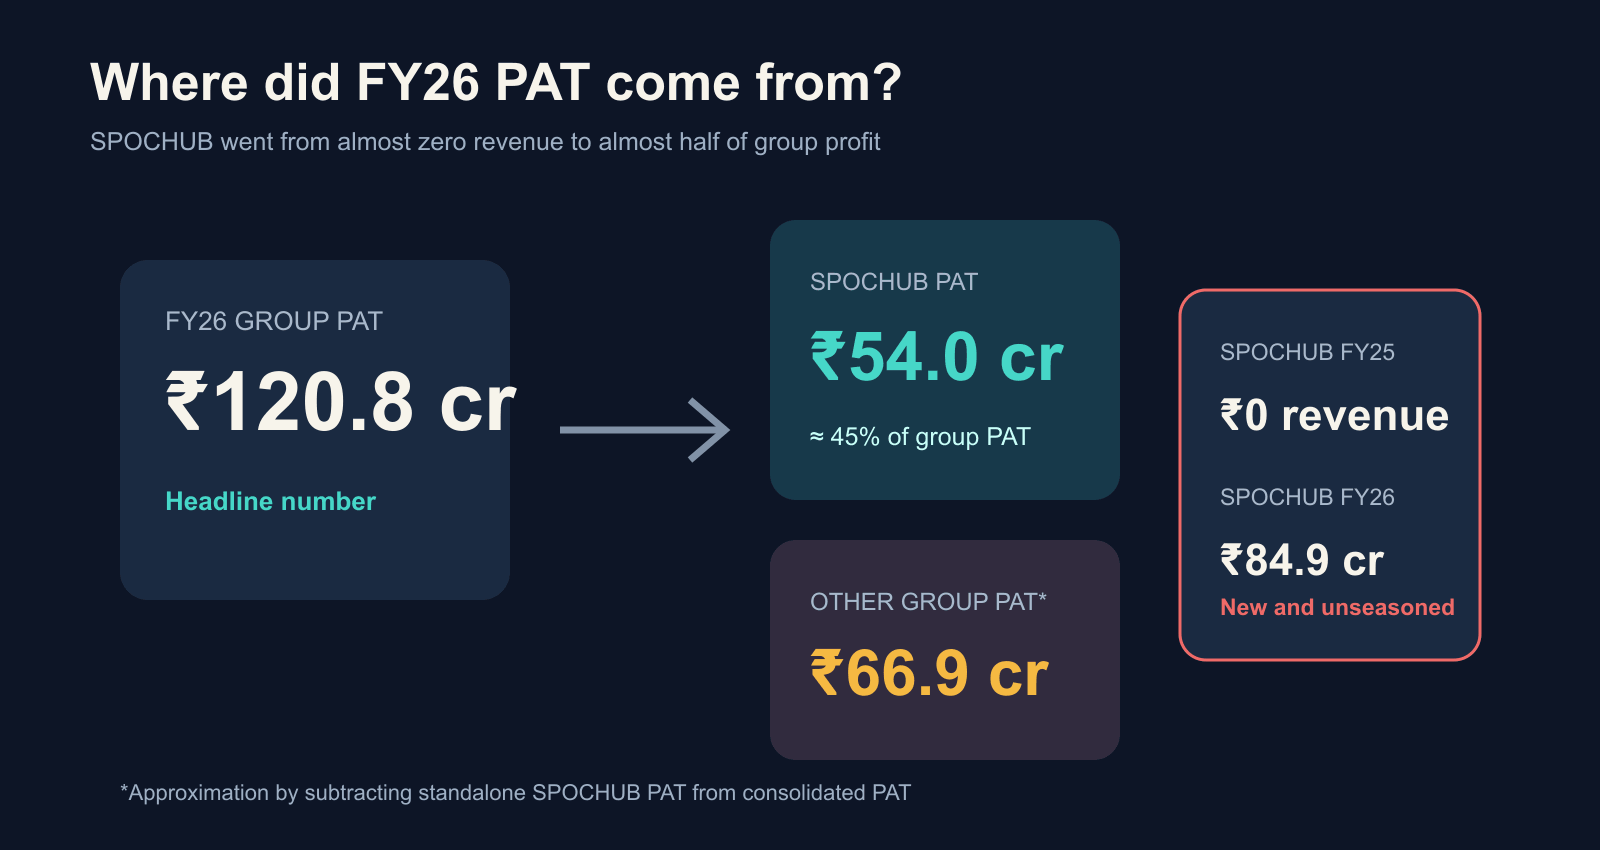
The part that makes me pause is the margin. SPOCHUB earned ₹53.96 crore of PAT on ₹84.95 crore of revenue, a 63.5% net-profit margin. That is an exceptional number for a newly active cloud and managed-services subsidiary.
The ₹1,176.6 crore GPU customer advance does not explain this profit. The RHP says the advance will be amortised only after the GPU project goes live. It had not created FY26 revenue or PAT.
So what exactly produced SPOCHUB’s ₹84.95 crore of revenue and 63.5% margin?
Was this revenue from the ₹75.24 crore UAE customer disclosed elsewhere in the RHP? Was it a separate contract? Was there a one-time implementation or trading element? What expenses sat in ESDS or another subsidiary rather than SPOCHUB? The RHP does not connect these dots.
There is another governance question.
On May 26, 2025, ESDS sold 200 SPOCHUB shares, representing 1% of the subsidiary, to promoter Piyush Somani for ₹0.002 million, which is ₹2,000. The RHP states this plainly.
Ten months later, SPOCHUB reported ₹53.96 crore of FY26 PAT and ₹54.21 crore of net worth. The promoter’s 1% personal interest therefore represented approximately ₹53.96 lakh of FY26 PAT and ₹54.21 lakh of book value.
That does not prove the ₹2,000 transaction was unfair when it occurred. SPOCHUB was dormant at the time and the transformation may not have been foreseeable. But the timing is exactly why an investor should ask for the valuation basis and the commercial chronology.
Why did the promoter receive a direct personal interest in the subsidiary that would become the vehicle for ESDS’s most consequential transaction? When did discussions for the UAE customer advance and SharonAI GPU capacity begin? Why should future public shareholders own 99% of this subsidiary while the promoter personally owns the remaining 1%?
There is nothing wrong with a new project generating profit. The problem is using one year’s consolidated PAT as though every rupee has the same history, recurrence and risk.
The revenue mix shows the same pattern.
IaaS grew only 1.8% in FY26
SaaS revenue declined 14.2%
Managed services grew 157.2%
The RHP says ₹75.24 crore of managed-services revenue came from a new enterprise customer outside India. Without that customer, FY26 growth would have looked much more ordinary.
Red flag 2: one overseas customer disappeared, another of almost the same size appeared
Customer concentration is not a theoretical risk here. We have just seen it move the reported numbers.
In FY25, a Russian BFSI customer generated ₹72.81 crore, equal to 20.15% of group revenue. The RHP says this customer’s revenue fell to ₹13.24 crore in FY26 because sanctions reduced its need for ESDS’s services.
In FY26, a new UAE enterprise customer became ESDS’s largest customer and generated ₹75.24 crore, equal to 15.93% of group revenue.

The amounts are strikingly similar.
FY25 group revenue grew by ₹74.82 crore over FY24. The Russian customer generated ₹72.81 crore in FY25, equivalent to roughly 97% of that year’s total revenue increase.
In FY26, revenue from the Russian customer fell by ₹59.57 crore. The new UAE customer contributed ₹75.24 crore and more than replaced the decline.
I want to be explicit about what the evidence does and does not show. There is no evidence in the RHP that the Russian and UAE customers are related. I am not alleging that revenue was rerouted or that the contracts are improper.
The legitimate investor questions are simpler.
How did ESDS win a new overseas account of almost exactly the size of the sanctioned account within one year?
What is the identity and credit quality of the new customer?
What is the contract duration, minimum commitment and termination right?
Is the UAE customer the source of SPOCHUB’s FY26 profit, the GPU advance, both, or neither?
How much of the FY26 margin is repeatable?
When one or two overseas customers can explain most of the incremental revenue, “cloud growth” is not enough of an answer.
Retention below 100% is not software-quality
Revenue retention was 128.2% in FY24, 96.6% in FY25 and 94.9% in FY26.
A figure below 100% means the previous customer cohort produced less revenue than it did a year earlier. New customers more than compensated for that decline, but existing customers were not expanding spend on an aggregate basis.
This is another reason I do not regard ESDS as a high-quality software compounder. I would not give it the same multiple as a business where existing customers naturally spend more each year.
R&D expense also fell from 4.4% of revenue in FY24 to 1.3% in FY26. A company presenting itself as an AI-enabled, proprietary cloud platform should explain whether this is efficiency, capitalisation, a temporary pause or underinvestment.
Red flag 3: the ₹1,368 crore cash-flow optical illusion
FY26 reported operating cash flow was ₹1,367.7 crore against PAT of ₹120.8 crore. At first glance, this looks like extraordinary cash conversion.
It is not.
FY25 operating cash flow was ₹162.6 crore. The FY26 figure therefore increased by about ₹1,205 crore.
Other current and non-current liabilities increased by ₹1,181.3 crore, mainly because SPOCHUB received a ₹1,176.6 crore customer advance. That liability increase explains roughly 98% of the year-on-year increase in operating cash flow.
Subtracting only the disclosed advance leaves diagnostic operating cash flow of about ₹191 crore. Subtracting the entire liability increase leaves about ₹186.5 crore. Either method is far more useful than treating ₹1,368 crore as recurring cash generation.
After ₹125.9 crore of capital expenditure, cash flow was about ₹60.6 crore.
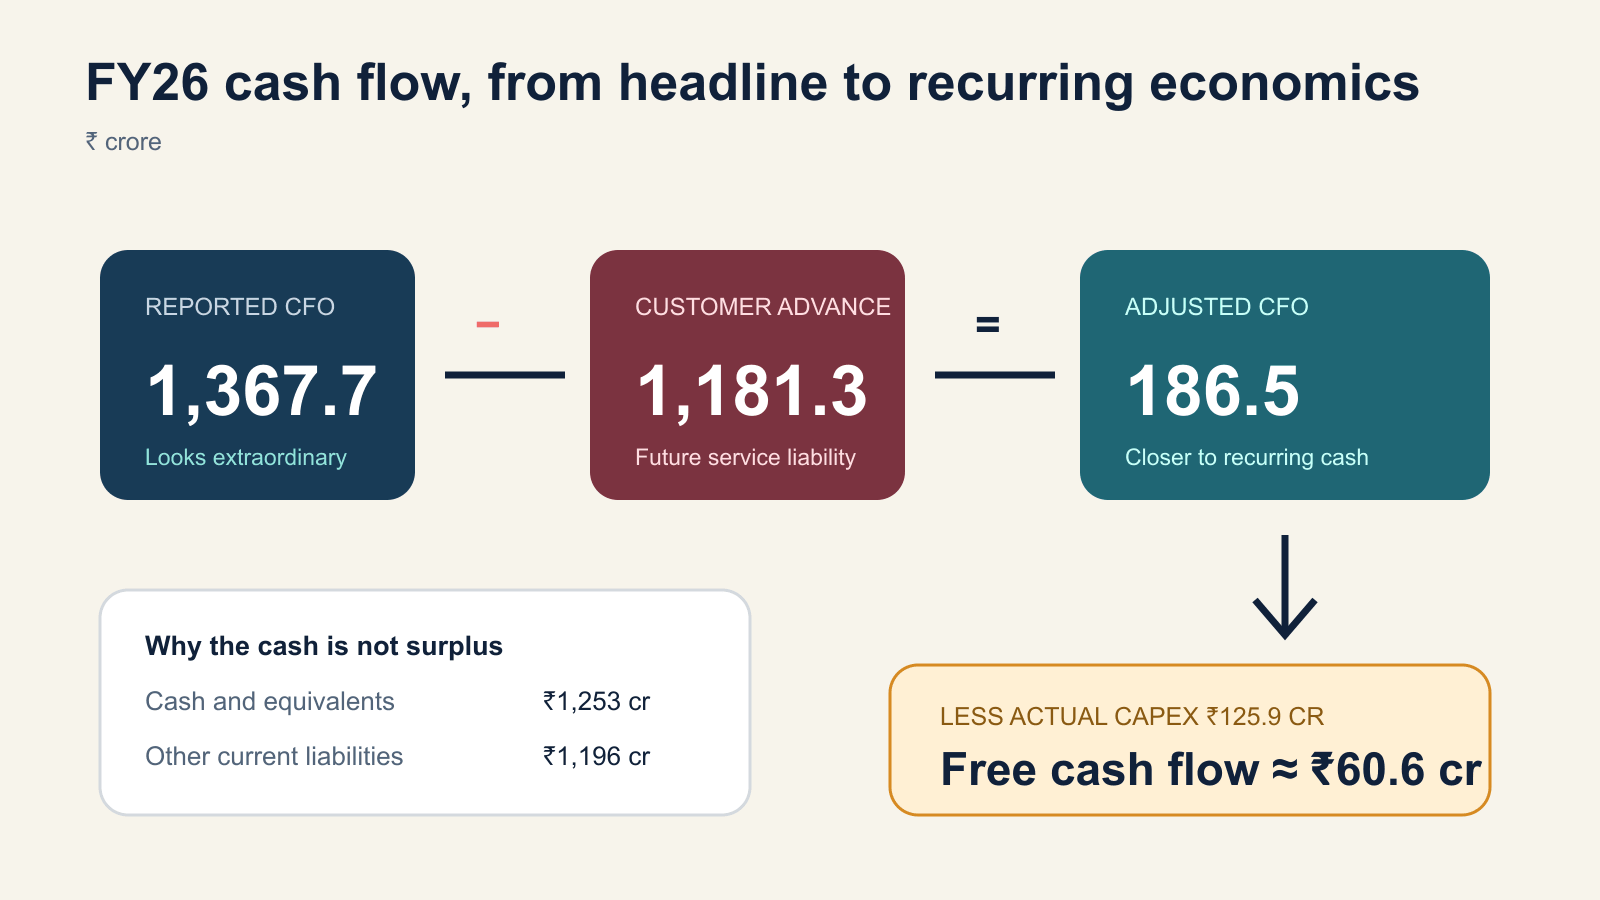
This does not mean the underlying cash conversion was poor. Adjusted operating cash flow of ₹186 crore to ₹191 crore against PAT of ₹121 crore is respectable. The point is that the headline number is economically misleading.
The same adjustment is necessary when looking at the balance sheet.
ESDS reported around ₹1,253 crore of cash and cash equivalents at March 2026. But other current liabilities were around ₹1,196 crore. Almost all the apparent net cash arrived with a future service obligation attached.
I would not subtract the entire cash balance from enterprise value as though it were surplus cash available to shareholders.
Receivables also need watching. The reported DSO improved to 79 days from 101 days. However, that calculation uses billed receivables. Including ₹63.4 crore of unbilled receivables takes the effective collection exposure to roughly 128 days. The loss allowance was ₹34.6 crore, which is material relative to the receivable book.
Government and PSU customers contributed 27.4% of FY26 revenue. These can be sticky customers, but collections can be slow and working capital can remain locked for long periods.
Red flag 4: the $1.25 billion GPU agreement is a liability, not an order
This is the most important section in the entire analysis.
ESDS says it entered into a five-year strategic AI cloud agreement with an Australia-based neocloud provider for 8,208 NVIDIA B300 GPUs and 17.83 petabytes of storage.
Read casually, “$1.25 billion contract” sounds like ESDS won a giant order.
The counterparty’s US filing shows the opposite side of the transaction.
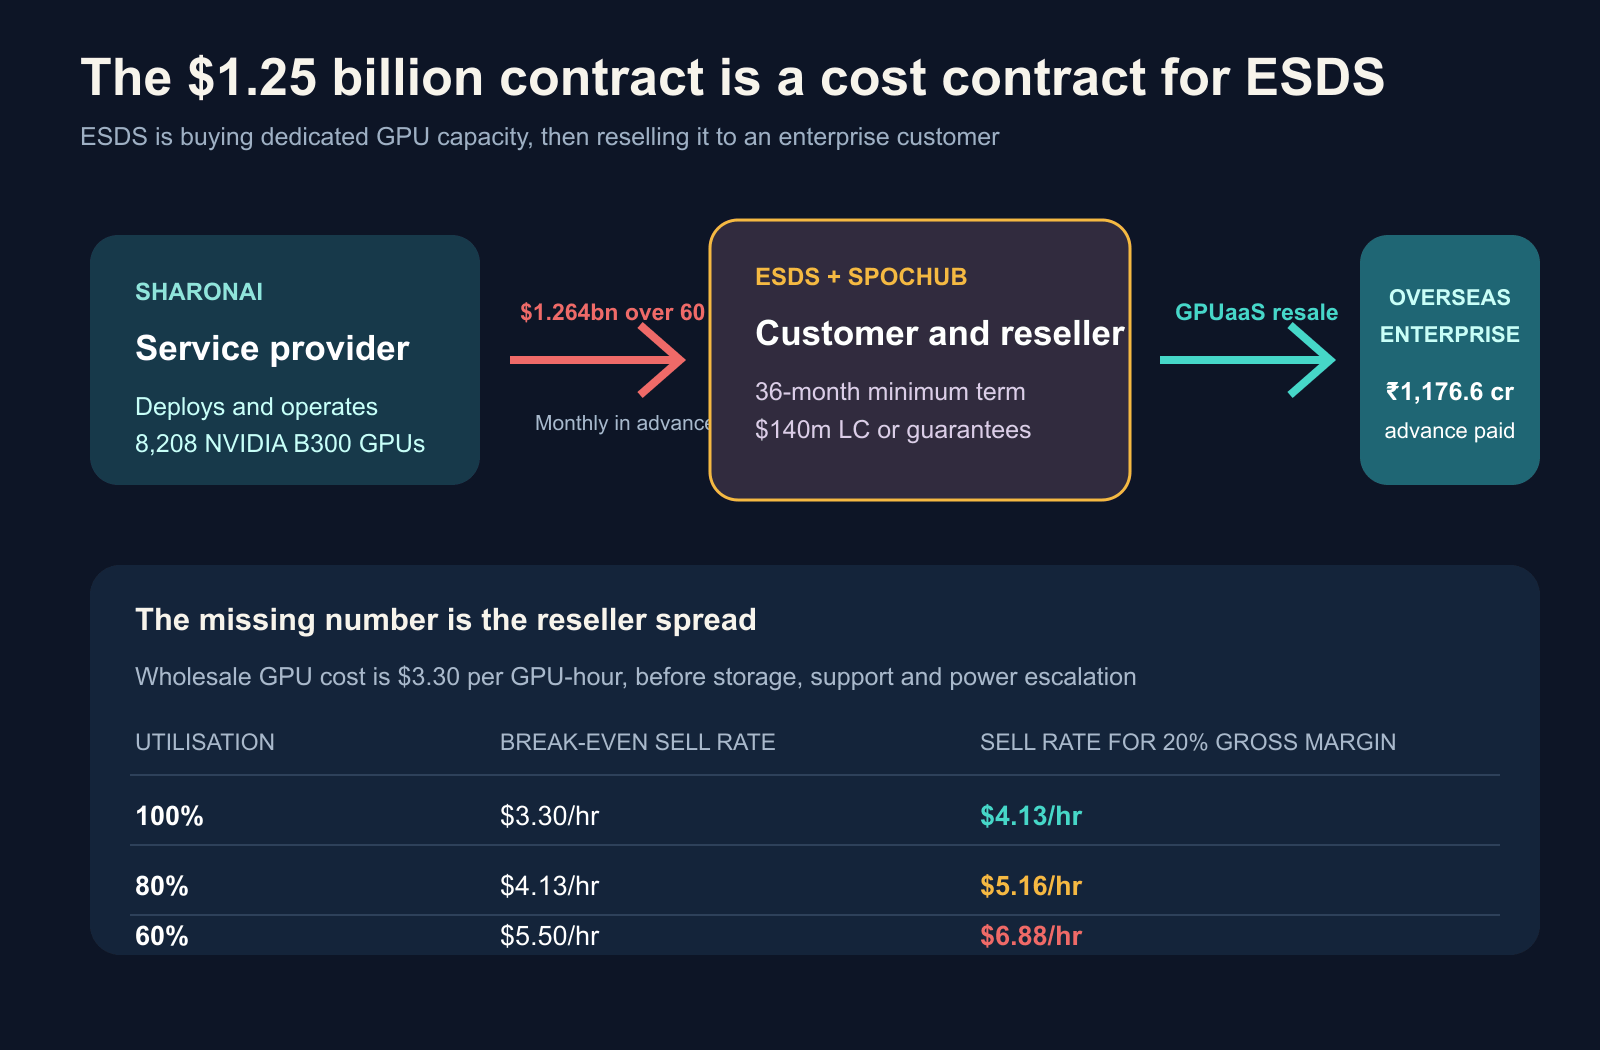
In the SharonAI 8-K, ESDS, SPOCHUB and ESDS Cloud FZ are defined as the Customer. SharonAI is the Service Provider.
The detailed service agreement says:
SharonAI grants ESDS exclusive access to 8,208 B300 GPUs
Total payment over 60 months is about $1.264 billion
The GPU component is priced at $3.30 per GPU-hour
Fees are invoiced monthly in advance
ESDS cannot terminate for convenience during the first 36 months
ESDS must provide letters of credit or bank guarantees aggregating $140 million
Electricity-cost increases can be passed through
Early termination payments apply
SharonAI calls it a five-year take-or-pay customer contract. For SharonAI, it is contracted revenue. For ESDS, it is contracted input cost.
This does not mean the deal is necessarily bad for ESDS.
The RHP separately says SPOCHUB secured a GPUaaS contract with an enterprise customer outside India and received an advance of ₹1,176.6 crore. That may be a back-to-back arrangement where ESDS resells the compute at an attractive spread.
The advance is encouraging, but it is not revenue and it is not profit. The RHP says it will be amortised only after the project goes live.
The problem is that we are not given the information required to calculate that spread.
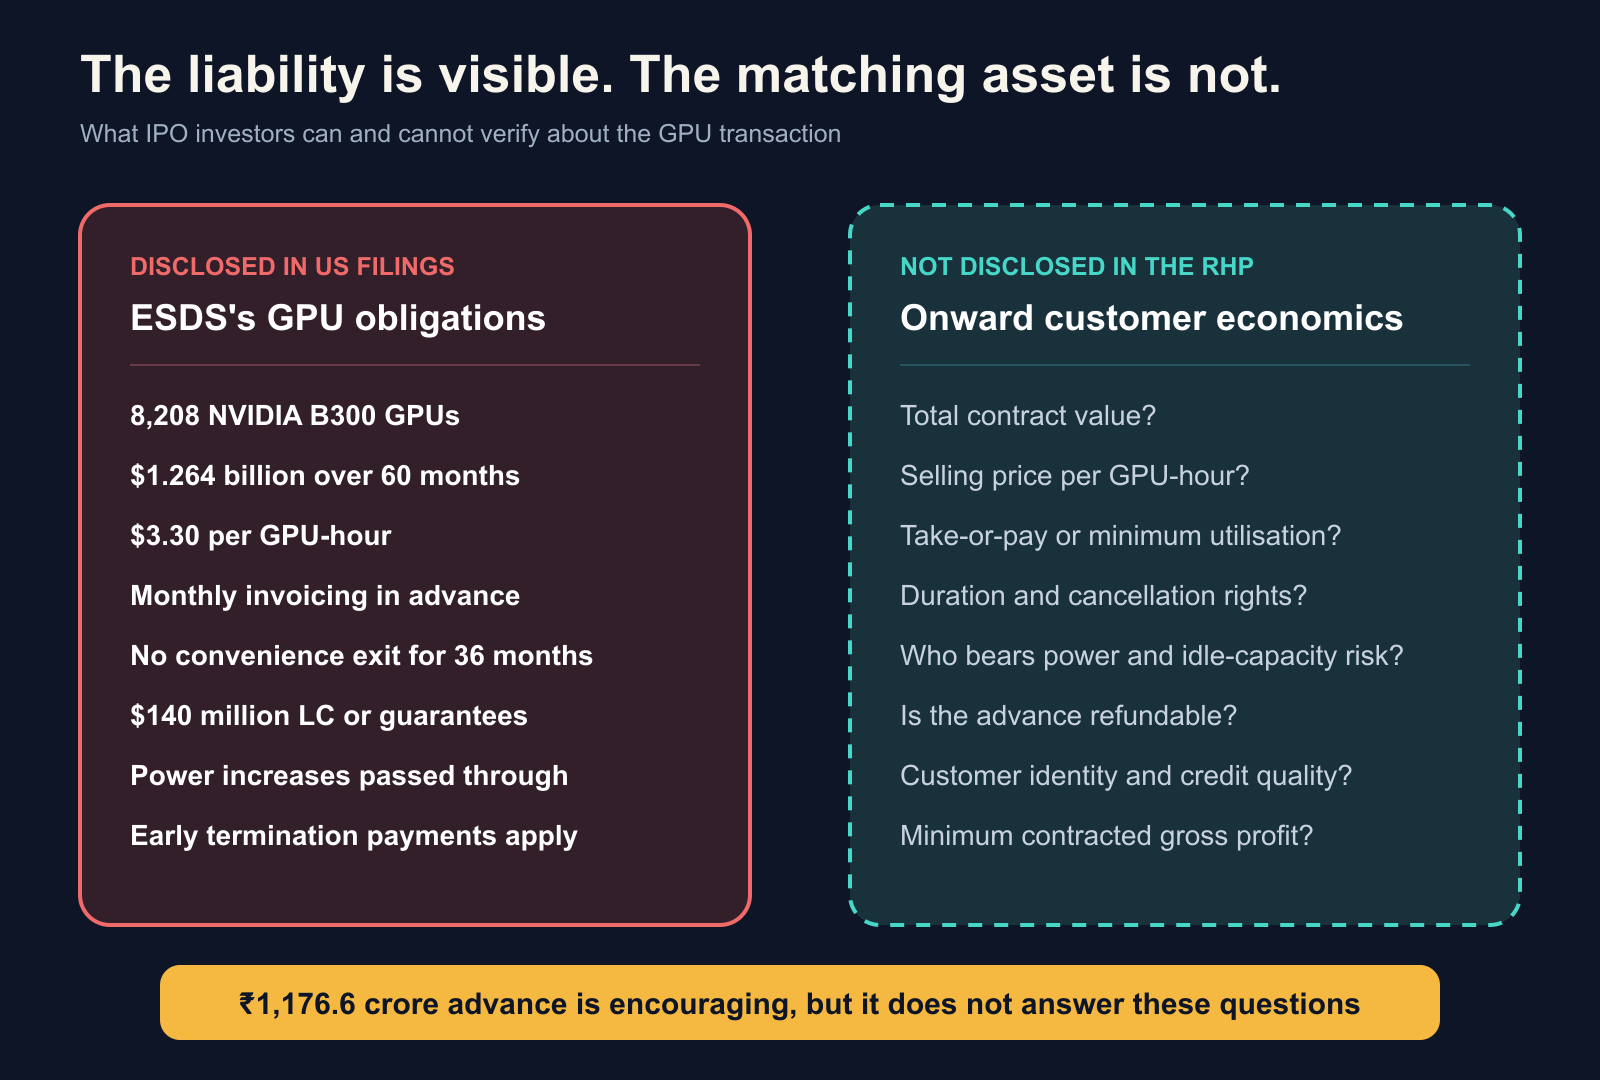
We need to know:
Total value of the onward customer contract
Price charged per GPU-hour
Whether the customer has a take-or-pay obligation
Contract duration and termination rights
Who bears underutilisation and power-price risk
Credit quality of the onward customer
Whether the ₹1,176.6 crore advance is refundable under any circumstance
Without those terms, assigning a large value to the project is speculation.
The disclosure asymmetry is the heart of my discomfort.
On the cost side, investors can read the number of GPUs, price per GPU-hour, five-year payment schedule, minimum term, letters of credit, power-price pass-through and early-termination consequences.
On the revenue side, investors cannot see the total customer-contract value, minimum committed utilisation, unit selling price, cancellation provisions or minimum gross profit.
We can see ESDS’s liability clearly. We cannot see the matching asset clearly.
Think of it like an airline leasing an entire aircraft for five years. A travel company has paid a large deposit to reserve seats. That sounds encouraging, but an investor still needs to know the ticket price, how many seats are guaranteed, whether the customer can cancel, and who pays when fuel becomes expensive.
The wholesale GPU economics are demanding.
At 100% utilisation, the $3.30 GPU cost requires a resale rate of about $4.13 per hour to earn a 20% gross margin. At 80% utilisation, the required rate rises to about $5.16. At 60% utilisation, it rises to about $6.88. These figures exclude storage, support, networking and any electricity-price adjustment.
The agreement also has counterparty execution risk. SharonAI reported $1.86 billion of cash at June 2026 after large fund raises, which is reassuring. Yet its August 2026 prospectus says the ESDS deployment needs about $733 million of capital expenditure, with 70% to 80% targeted through asset-level debt, and no binding debt financing had been finalised at that date.
The cluster was targeted for delivery in September 2026. I would rather see it commissioned, billed and paid for before capitalising five years of hoped-for profit.
Management’s interviews make the GPU disclosure problem worse
After writing the first draft, I watched and read Piyush Somani’s latest IPO interviews. They did not give me comfort. They made me more cautious.
The core problem is how easily a cost commitment has been allowed to sound like an order win.
In the CNBC Awaaz interview, the anchor introduced the SharonAI arrangement as an ₹11,831 crore order win and asked when ESDS would begin seeing revenue. Somani went along with that framing, saying the order would go live in Q3 and revenue would build from there. He also said the customer had committed the factory to ESDS for seven years.
The English CNBC-TV18 interview produced a very different clarification. When the anchor asked whether the $1.25 billion was revenue ESDS would earn, Somani answered, “No, this is what we have to pay to Sharon AI, so this is the cost.” When asked for the corresponding revenue, he said it had not been disclosed.
Moneycontrol’s profile describes the arrangement as having a total potential contract value of $1.25 billion, followed by revenue generation from Q3 FY27. Inc42’s interview similarly calls it a $1.25 billion agreement under which SharonAI will own and operate the GPUs for ESDS.
The signed US agreement is much clearer. ESDS is the customer. SharonAI is the service provider. The $1.264 billion is the scheduled amount ESDS must pay for compute and storage over 60 months.
This is not a minor wording issue. It is the difference between a company winning $1.25 billion of revenue and a company committing to purchase $1.25 billion of capacity. ESDS may have a profitable onward contract, but that value and margin have not been disclosed.
The duration has also been communicated imprecisely. In the Hindi interview, Somani called it a seven-year commitment. In the English interview, while explaining the cost, he verbally moved from seven years to five years and eventually settled on five.
The signed agreement resolves the legal question. It has a fixed 60-month term. Some media reports refer to seven years because there may be an option to extend it by two years. The fair reading is five binding years plus a possible two-year extension, not seven years of disclosed or guaranteed revenue. The legal document is clear. The IPO communication around it has not been.
Then comes the strangest claim.
In a CNBC-TV18 interview, Somani said GPUs were currently behaving like appreciating assets because their prices had risen over the previous six months. He also cited service prices of $5 to $6 per GPU-hour and said rates were rising 30% to 35% every three months.
A temporary shortage can raise hardware purchase prices and cloud rental rates. That does not make computing hardware an appreciating asset in the normal investment sense. GPUs face new architectures, improving performance per watt, changing software support and eventual obsolescence. Scarcity pricing can reverse when supply catches up or customers move to newer chips.
There is an additional mismatch here. SharonAI owns the 8,208 GPUs. ESDS is purchasing access to their capacity. If the physical assets rise in resale value, that upside belongs primarily to their owner. ESDS’s economics depend on the spread between the contracted $3.30 input cost and the price it can collect from its onward customer, after utilisation, storage, networking, support and power costs.
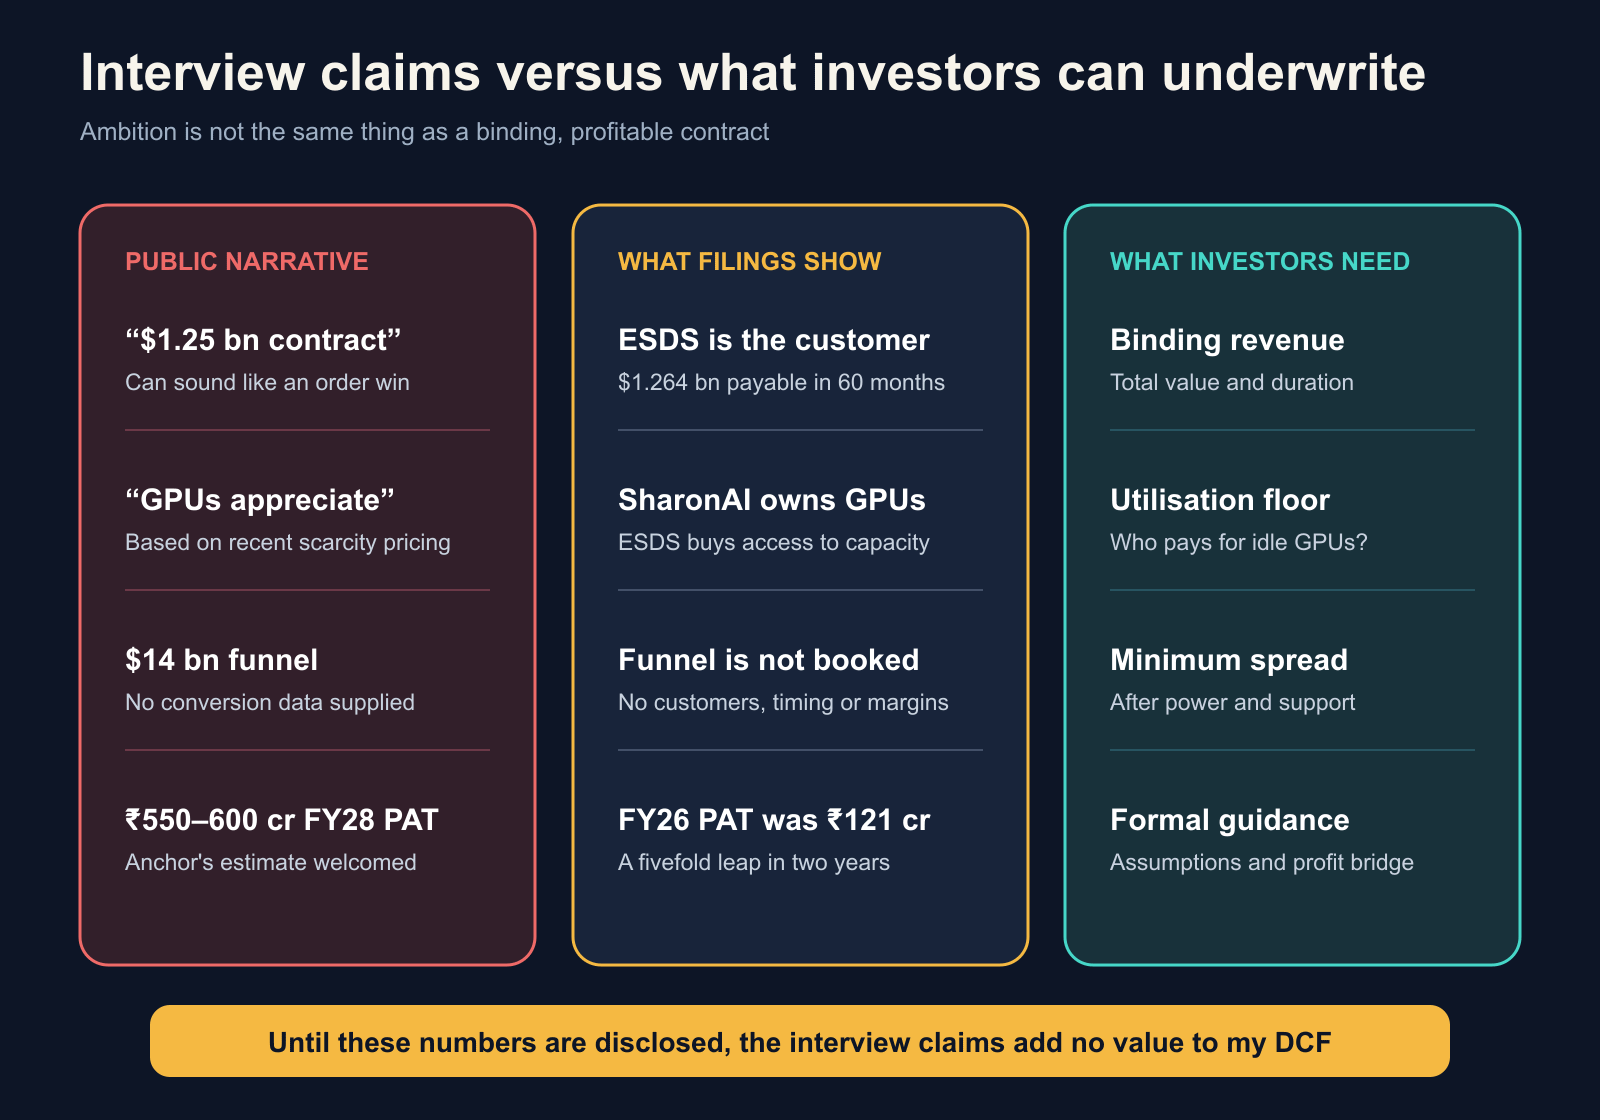
The same interview included several very large numbers:
A roughly $14 billion business funnel
Global neocloud targets of about 85% EBITDA margin, 40% PAT margin and 45% ROCE
A back-of-the-envelope suggestion from the anchor that ESDS could reach ₹550 crore to ₹600 crore of PAT by FY28
An ambition to move India’s “digital sovereignty score” from about 18 to 95 in 2,000 days
These statements may describe management’s ambition. They are not valuation inputs.
The ₹550 crore to ₹600 crore PAT exchange deserves special attention. That number was suggested by the anchor, not formally guided by ESDS. But instead of correcting or tempering it, Somani replied, “Definitely, we will be working towards that.”
₹550 crore to ₹600 crore of PAT would exceed ESDS’s entire FY26 revenue of ₹472 crore. It would require reported PAT to grow roughly five times in two years. Even allowing for the GPU project, that is an extraordinary outcome. A responsible valuation cannot treat an enthusiastic response during a television interview as earnings guidance.
A funnel is not an order book. Investors were not given its customer composition, probability of conversion, delivery period, financing requirement or expected margin. Economics achieved or targeted by global neocloud companies do not automatically belong to ESDS, particularly when ESDS is buying capacity under a large fixed contract and has not disclosed its resale economics.
The digital-sovereignty score may be a useful internal advocacy tool, but no independent methodology or benchmark was supplied in the interview. I would assign it no value in an investment model.
The storytelling itself deserves a discount
One founder story is not a financial red flag by itself, but it tells us something about the style of communication.
In his Business Today interview, Somani said ESDS was almost bankrupt in October 2006, with nothing left in his bank account and the workforce reduced from 60 people to 25. He then said that by January 2007, only three months later, he made down payments on five Maruti Swift cars and gifted them to his best-performing employees.
That may have happened exactly as described. Perhaps a large customer paid, collections arrived or financing became available. The problem is that the missing financial bridge is the entire interesting part of the story.
This pattern repeats throughout the IPO narrative. We are given dramatic starting points and spectacular destinations. The bridge between them is often thin.
Nearly bankrupt to five employee cars in three months
A $1.264 billion cost commitment discussed as a giant deal
₹121 crore of PAT potentially becoming ₹550 crore to ₹600 crore in two years
A $14 billion funnel without conversion economics
A digital-sovereignty score moving from 18 to 95 in 2,000 days
I do not value a company on stories. I value the contractual cash flows between the beginning and the end. In ESDS’s most important new project, those cash flows remain only half visible.
This does not prove wrongdoing. It does show why I am unwilling to rely on promotional language. When a company enters a commitment of this size just before asking the public for money, management should make the economics easier to understand, not easier to misunderstand.
What is the IPO money buying?
The ₹720 crore issue is entirely fresh equity, but the absence of an offer for sale does not make the IPO low risk.
₹576 crore is allocated to Indian cloud and data-centre equipment:
₹266 crore for servers, including ₹170 crore for 20 B300 GPU systems and ₹96 crore for 80 conventional cloud nodes
₹83 crore for storage
₹52 crore for networking
₹175 crore for other infrastructure
The remaining amount is for issue expenses and general corporate purposes.
This domestic capex is separate from the Australian SharonAI service commitment.
The issue will materially expand ESDS’s capacity, but it also shows why the business cannot be valued as capital-light software. FY24 to FY26 cash capex was about ₹262 crore in total. The IPO-funded programme alone is more than twice that amount.
Servers also become obsolete. A B300 is exciting today, but future customers will demand newer chips. Depreciation is an economic cost, not an accounting nuisance.
Red flag 5: the governance footnotes deserve daylight
None of the following disclosures proves fraud. Some may resolve entirely in ESDS’s favour. But a forensic IPO review should not hide them in hundreds of pages of legal text.
Rating-agency non-cooperation
The RHP records multiple ratings when Acuité and CRISIL marked ESDS as “issuer not cooperating.” It explains that the company did not share information with the agency. Acuité also downgraded the long-term rating in December 2023 and again in March 2025.
The more recent picture improved. India Ratings assigned BBB+/Positive in July 2025, and CRISIL upgraded ESDS to BBB+/Positive in September 2025. That is credit-positive, but it does not erase the earlier disclosure habit. Public shareholders will depend on timely information long after the IPO roadshow is over.
Pending GST notice involving alleged fraudulent invoices
The RHP discloses a pending GST matter relating to FY20. The department alleged wrongful input-tax credit of ₹2.48 crore based on fraudulent invoices and issued a show-cause notice, with interest and penalty also claimed.
ESDS has sought transfer of the matter, citing parallel investigations on the same subject. The case is pending. This is an allegation by the tax department, not a finding of wrongdoing, but the language and nature of the notice are material enough for investors to know.
A former employee’s pending 1% share claim
A former employee has filed a civil suit against ESDS and Piyush Somani. He alleges that he was offered a 1% stake in 2015 and later received an ESOP grant, but did not receive the claimed shares. He seeks the shares or compensation of ₹18.48 crore. ESDS disputes the claim and the matter is pending before the Bombay High Court.
Again, this is an unresolved allegation. I am not deciding the case. I am saying a promised-equity dispute involving the promoter is relevant when evaluating governance.
The former subsidiary sold for ₹90,000
In August 2024, ESDS sold its entire 50% stake in ESDS Internet Services Private Limited to Vinod Rajmal Sancheti for ₹90,000, equal to face value. The former subsidiary had ₹38.84 crore of total assets and ₹6.88 crore of FY24 revenue.
Assets are not net worth. The company says a registered valuer certified the fair market value, so these figures alone do not prove that value was transferred cheaply. Still, the RHP does not give enough information in that passage to reconcile the ₹90,000 equity value with the asset and revenue base. I would want to see the subsidiary’s liabilities, net worth, profitability, valuation method and relationship with the buyer.
The important distinction is between an accusation and an unanswered question. I do not have enough evidence for the first. I have more than enough for the second.
Red flag 6: the valuation prices in answers we do not have
At the upper price band:
Post-issue shares are approximately 11.72 crore
Post-issue market capitalisation is approximately ₹5,028 crore
FY26 post-issue P/E is approximately 41.6 times
P/E on FY26 profit excluding SPOCHUB is approximately 75 times
Price to FY26 sales is approximately 10.6 times
Price to FY26 free cash flow after actual capex is approximately 83 times
Enterprise value to FY26 EBITDA is approximately 21 times if the customer-advance-backed cash is not treated as surplus
You may see an IPO P/E of roughly 36 times elsewhere. That divides ₹429 by the pre-issue FY26 EPS. The new shares dilute the per-share claim, so I prefer the post-issue market capitalisation divided by FY26 PAT.
The RHP identifies only E2E Networks as a listed peer. E2E reported a loss in FY26, which makes its P/E meaningless. Using E2E’s market capitalisation as the primary valuation anchor would replace analysis with circular optimism.
What growth is the market pricing in?
I ran a reverse DCF rather than pretending we can forecast the GPU project precisely.
Using a 13% required return, 5% terminal growth and ten years of explicit growth:
Starting from actual FY26 free cash flow of ₹60.6 crore, ₹429 requires roughly 31% annual free-cash-flow growth for ten years
If I generously treat depreciation as maintenance capex and start with normalised owner earnings of about ₹123 crore, ₹429 still requires roughly 21% annual growth for ten years
The conservative path requires year-ten free cash flow of about ₹912 crore. The generous path requires about ₹828 crore.
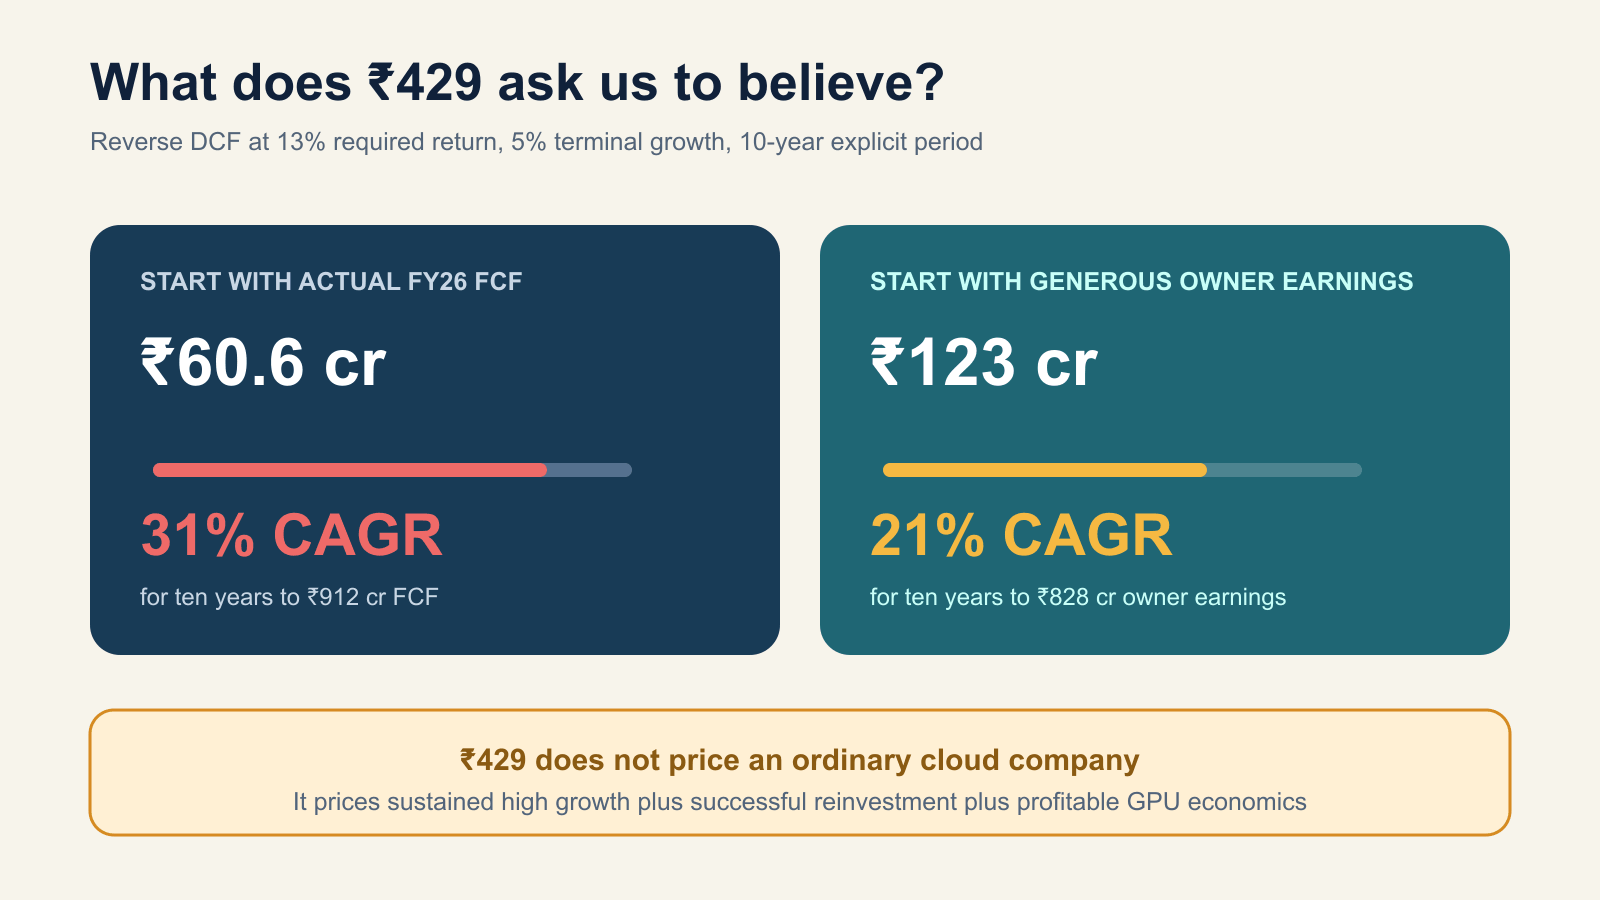
This is possible only if the new capital earns high returns, the core cloud business keeps compounding and the GPU project produces a healthy, durable spread.
It is not a valuation that leaves room for ordinary execution.
My scenario-based DCF
A single DCF number would be false precision, so I used three paths.
Bear case, ₹99 per share
I start with ₹61 crore of owner earnings, assume 15% growth for five years and 10% for the next five, use a 14% discount rate and 4% terminal growth.
This represents ordinary cloud growth, weaker retention and little economic value from the GPU project.
Base case, ₹249 per share
I start with ₹90 crore of normalised owner earnings, assume 20% growth for five years and 15% for the next five, use a 13% discount rate and 5% terminal growth.
This assumes the Indian cloud business scales well, IPO capex earns respectable returns and the GPU project contributes, but does not become a gold mine.
Bull case, ₹603 per share
I start with ₹123 crore of owner earnings, assume 25% growth for five years and 20% for the next five, use a 12% discount rate and 5.5% terminal growth.
This requires excellent utilisation, strong GPU reseller economics, durable customer contracts and successful reinvestment of the IPO proceeds.
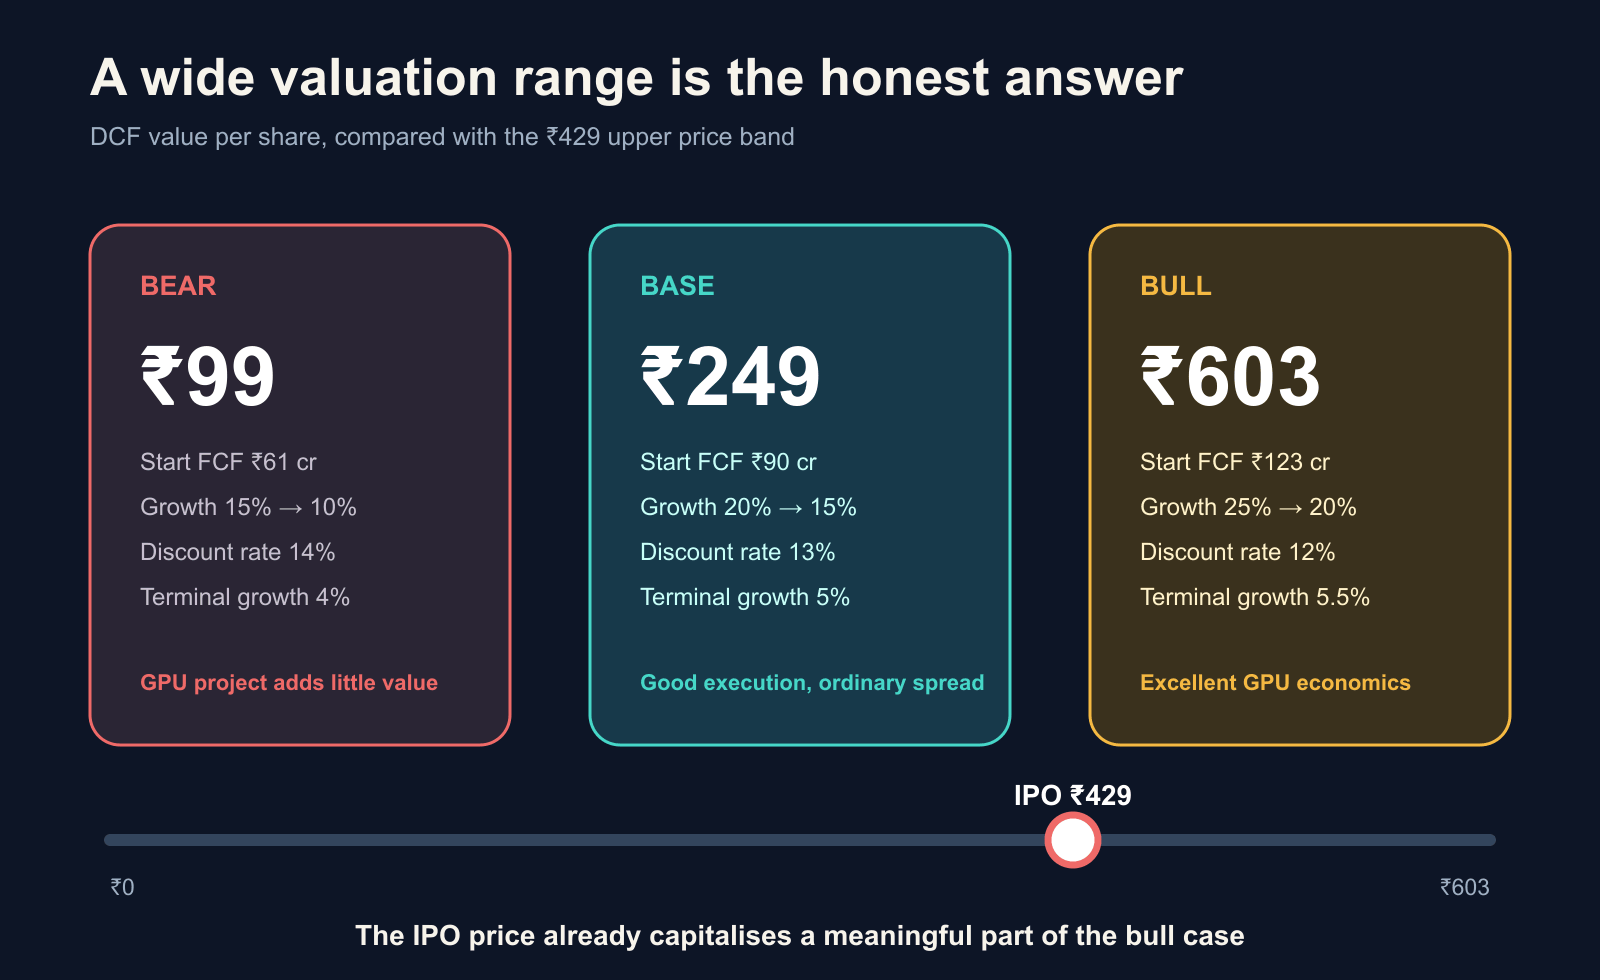
The issue price sits above my base case and already capitalises a meaningful part of the bull case.
Another way to see this is to ask what FY31 PAT is required for a 12% annual return from ₹429.
At a 20 times exit P/E, FY31 PAT must be about ₹443 crore
At a 25 times exit P/E, FY31 PAT must be about ₹355 crore
At a 30 times exit P/E, FY31 PAT must be about ₹295 crore
That is a 20% to 30% five-year PAT CAGR from reported FY26 profit. Measured from the approximate ₹66.9 crore of non-SPOCHUB profit, the required CAGR is roughly 35% to 46%.
The case for staying away, in one list
The largest new project involves a five-year, $1.264 billion compute purchase commitment whose onward margin is undisclosed
Management’s media narrative has allowed that purchase commitment to sound like an order, while the $14 billion funnel and global neocloud margins remain unsupported by contract-level disclosure
Nearly 45% of FY26 PAT came from a subsidiary with no prior-year revenue and a 63.5% PAT margin
The promoter bought 1% of that subsidiary for ₹2,000 ten months before it reported ₹53.96 crore of PAT
Reported cash flow and net cash are inflated by a customer advance
Revenue retention was below 100% in FY25 and FY26
IaaS barely grew and SaaS declined in FY26
Customer concentration is high, with the largest customer at 15.9% and the top ten at 45.4% of revenue
A Russian BFSI customer’s revenue fell from ₹72.8 crore in FY25 to ₹13.2 crore in FY26, while a new UAE customer contributed ₹75.24 crore
Receivables and unbilled revenue remain material
R&D intensity declined sharply
Hardware obsolescence and continuing capex limit the value of headline EBITDA
The rating history includes earlier issuer non-cooperation and downgrades, even though ratings improved later
The pending GST notice, former employee equity claim and ₹90,000 subsidiary disposal add governance questions
What would change my mind?
I would revisit ESDS after seeing five things.
First, commissioning of the 8,208-GPU Australian cluster and evidence that SharonAI has completed the financing and delivery.
Second, disclosure of the onward customer economics, or at least enough information to estimate ESDS’s minimum contracted gross profit after compute, storage, power and financing costs.
I would also want management to reconcile every public description of the SharonAI arrangement in one plain table, separating ESDS’s fixed cost, the onward customer’s binding revenue commitment, the five-year fixed term, any optional extension and the minimum contracted profit spread.
Third, a clear reconciliation of SPOCHUB’s FY26 revenue, extraordinary margin, customer relationships and the basis on which the promoter acquired 1% for ₹2,000.
Fourth, two or three quarters of cash flow after removing customer advances, with billed and unbilled receivables under control.
Fifth, revenue retention returning above 100% while the Indian core business grows without relying on one new overseas customer.
Price matters, but price alone will not solve my governance discomfort. At ₹429, investors are being asked to underwrite the optimistic answers before they are visible. Even at a much lower price, I would first want the disclosures above.
Final verdict
ESDS is not a simple data-centre landlord. It has long operating history, regulated-customer references and exposure to a genuine sunrise market. Those facts are interesting. They are not enough for me to conclude that this is already a high-quality cloud franchise.
It is also not a capital-light software compounder. It owns and rents hardware, spends heavily on capacity, collects slowly from parts of its customer base, and has now entered a very large fixed GPU-capacity commitment.
The ₹1,176.6 crore customer advance is encouraging. It is not enough information to value the project. Until we know the onward pricing and risk-sharing, the $1.25 billion headline should make us more careful, not more excited.
Management’s interviews did not reduce that uncertainty. Describing GPUs as appreciating assets, discussing a $14 billion funnel and citing global neocloud margins does not substitute for disclosing ESDS’s own contracted revenue, utilisation protection and minimum profit.
The SPOCHUB transformation makes me unwilling to give management the benefit of the doubt. A dormant subsidiary moved to a 63.5% PAT margin, produced 45% of group profit, received an advance larger than the entire IPO valuation of many listed companies, and carries a direct 1% promoter interest acquired for ₹2,000 shortly before the transformation. Even if each fact has an innocent explanation when viewed separately, the combination is too much for me to ignore.
At ₹429, my answer is no. I would stay away, and I do not think my subscribers should apply. The IPO asks us to pay today for GPU economics that have not been disclosed, subsidiary profits that have not been adequately explained, and governance questions that remain open.
The cloud industry may be a sunrise industry. That does not make every cloud IPO investible.
This is my personal research and not investment advice. Please read the RHP and do your own work before making any decision.
Google result on SharonAI Fraud: Sharon AI ($SHAZ) has faced market scrutiny and skepticism regarding its high-profile partnerships and explosive valuation, though no official legal charges or formal findings of fraud have been established against the company.Key Context and Scrutiny Surrounding Sharon AINvidia Equity Clarification: Sharon AI initially described Nvidia as a strategic shareholder in an early filing, but later corrected the disclosure via an SEC 8-K filing to clarify that Nvidia holds no equity stake in the company, only maintaining a compute and technology partnership.Circular Financing Concerns: Market watchers and reports have grouped Sharon AI into broader investor anxieties surrounding "circular deals"—where major hardware providers like Nvidia help finance or support cloud startups that in turn purchase their chips, inflating apparent organic demand.Aggressive Expansion Claims: The company rapidly scaled its contracted targets (announcing massive multi-billion-dollar deals and data center capacities in Australia and New Zealand), which fueled intense skepticism among short-sellers and market analysts questioning the operational backing behind such rapid projections.